Insurance in San Juan TX: Complete Guide to Protecting Your Home, Car, and Family
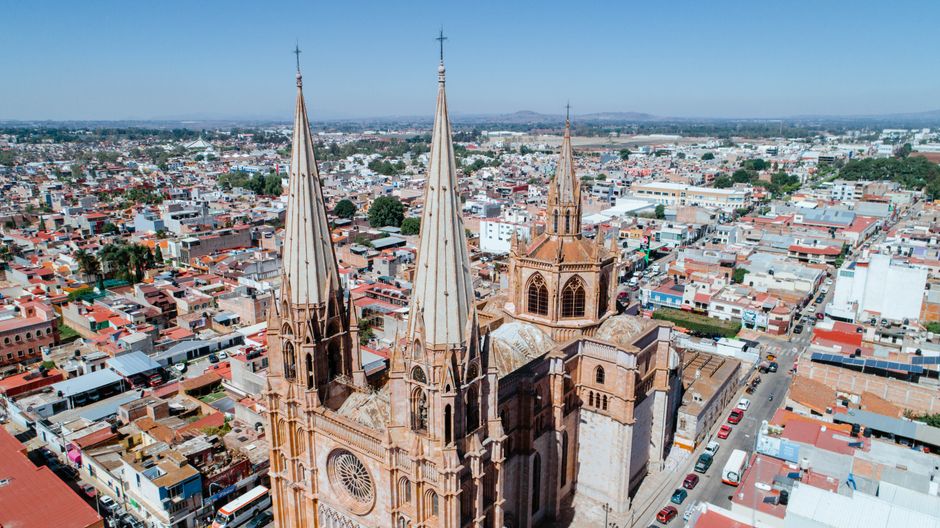
Have you ever looked at your insurance policies and wondered if you’re actually protected, or just paying for peace of mind? You’re not alone. Living in San Juan, Texas means balancing the vibrant Rio Grande Valley lifestyle with real-world risks—from sudden hailstorms that can damage your roof to unexpected health issues that could strain your finances. Insurance isn’t just another bill; it’s the safety net that lets you enjoy San Juan’s community events, local businesses, and family time without constantly worrying about “what if.”
Whether you’re new to the area or re-evaluating your coverage, navigating insurance in San Juan TX can feel overwhelming. You’ve got different providers, confusing terms, and policies that seem designed to make your eyes glaze over. But getting it right matters—proper coverage means your family stays secure, your assets are protected, and you can handle life’s surprises without financial devastation.
In this comprehensive guide, we’ll walk through everything you need to know about insurance in San Juan, from homeowners and auto coverage that considers our unique weather patterns to health insurance options that work with local providers. You’ll learn how to assess your actual needs, compare policies effectively, and avoid common pitfalls that leave people underinsured when they need protection most.
Key Takeaways
- San Juan’s specific risks require tailored coverage—standard policies often miss Valley-specific issues like windstorm damage or border-proximity considerations
- Bundle strategically to save 15-25% without sacrificing coverage quality, especially with local providers who understand the area
- Review policies annually—property values and risk factors in Hidalgo County change faster than many realize
- Work with agents who know South Texas regulations—Texas insurance laws have unique provisions affecting claims and coverage
- Don’t skip flood insurance even if you’re not in a designated flood zone—Valley drainage issues make this essential protection
- Health insurance networks matter—ensure your preferred San Juan doctors and McAllen specialists are in-network before committing
- Document everything meticulously—from home inventories to auto accident details, proper records speed claims processing significantly
Understanding Insurance Needs in San Juan TX
San Juan isn’t just another Texas town—it’s part of the Rio Grande Valley’s unique ecosystem with specific insurance considerations. The subtropical climate brings both sunshine and severe weather risks, while our proximity to the border creates distinctive economic and demographic factors affecting insurance markets. When you’re evaluating insurance in San Juan TX, you need to think beyond generic coverage and consider what actually protects your life here.
Homeowners Insurance: More Than Just Fire Protection
Your home in San Juan faces different threats than houses in Dallas or Houston. Yes, you need standard fire and theft coverage, but Valley homeowners should pay special attention to wind and hail protection. Those sudden summer storms can damage roofs, windows, and siding faster than you’d expect. Many standard policies have separate windstorm deductibles that can be percentage-based rather than fixed amounts—meaning you could be responsible for thousands more than anticipated if a serious storm hits.
Consider this: a $200,000 home with a 2% wind deductible means you pay the first $4,000 of wind-related damage out of pocket. That’s why understanding your policy’s fine print matters. Additionally, San Juan’s older neighborhoods might have plumbing systems that insurance adjusters scrutinize more carefully. Documenting recent updates to your electrical, plumbing, and roofing systems can prevent coverage disputes later.
Editorial Insight: “Many San Juan residents don’t realize their homeowners insurance might exclude certain types of water damage that are common here. Sump pump failure, sewer backups, and gradual leaks often require separate endorsements. Review your policy’s water damage section line by line—if you see ‘seepage’ or ‘gradual leakage’ as exclusions, ask about adding water backup coverage.”
Auto Insurance in the Valley Context
Driving in Hidalgo County comes with its own considerations. Higher-than-average uninsured motorist rates mean your uninsured/underinsured motorist coverage isn’t optional—it’s essential protection. Texas law requires only liability coverage, but that leaves you vulnerable if someone without adequate insurance hits you. Given San Juan’s location between McAllen, Pharr, and Edinburg, you’re likely driving in heavier traffic areas regularly, increasing your collision risk.
Comprehensive coverage matters too. The Valley’s heat can be brutal on vehicles, increasing the likelihood of mechanical failures that might lead to accidents. Some insurers offer roadside assistance endorsements that make sense given our region’s spread-out geography—if you break down between San Juan and Harlingen, you’ll appreciate that coverage.
Comparing Insurance Options in San Juan
Not all insurance providers understand San Juan’s specific needs. National companies might offer competitive rates initially, but their claims adjusters might not be familiar with Valley construction methods, local repair costs, or common issues here. Local and regional providers often provide better service because they’re physically present in the community and understand the context of claims.
| Provider Type | Best For | Key Advantages | Potential Limitations |
|---|---|---|---|
| National Carriers | Digital-first customers, multi-state coverage needs | 24/7 online access, extensive resources, nationwide networks | Less local knowledge, standardized claims handling |
| Regional Texas Providers | Valley-specific coverage, personalized service | Understand local risks, faster local claims response, community presence | May have fewer digital tools, smaller network |
| Local San Juan Agencies | Face-to-face service, deep community knowledge | Hyper-local expertise, relationship-based service, knows local contractors | Limited to their carrier partners, may have fewer policy options |
| Direct Online Insurers | Price-sensitive shoppers, simple coverage needs | Lowest premiums, completely digital process | Minimal personal service, claims can be challenging |
Health Insurance: Navigating Valley Healthcare Networks
When evaluating health insurance in San Juan TX, the provider network might be more important than the premium cost. You need to check whether your preferred doctors at San Juan’s clinics, DHR Health, or McAllen Medical Center are in-network. Out-of-network care can cost dramatically more, turning what seems like affordable coverage into financial stress when you actually need care.
Many Valley residents qualify for subsidies through the Affordable Care Act marketplace, especially given our region’s income levels. Open enrollment periods matter, but qualifying life events (marriage, birth, job loss) create special enrollment opportunities. Don’t assume you have to wait if your situation has changed recently.
Deep Dive: Essential Coverage Types for San Juan Residents
Windstorm and Hail Insurance
This isn’t just an add-on in the Valley—it’s foundational protection. Texas Windstorm Insurance Association (TWIA) coverage might be necessary if you’re in a designated coastal area, but even inland San Juan properties need robust wind protection. Look for policies that cover both sudden damage and subsequent issues like water intrusion from compromised roofs. The best policies include “ordinance or law” coverage that pays for bringing damaged structures up to current building codes during repairs—essential in older San Juan neighborhoods where codes have evolved.
Flood Insurance: Don’t Skip This
Many San Juan residents mistakenly believe they don’t need flood insurance because they’re not in a FEMA-designated high-risk zone. Valley drainage systems can be overwhelmed during heavy rains, and even properties that have never flooded before can experience issues as development changes water patterns. National Flood Insurance Program (NFIP) policies have 30-day waiting periods, so you can’t wait until storms are forecasted. Private flood insurance options now offer competitive rates and sometimes better coverage than NFIP—worth exploring if you want higher limits or additional living expenses coverage.
Umbrella Liability Coverage
For San Juan families with assets to protect—whether that’s home equity, savings, or future earnings—umbrella insurance provides extra liability protection beyond auto and homeowners limits. Given today’s litigation environment, a serious accident could result in judgments exceeding standard policy limits. Umbrella coverage is surprisingly affordable (often $150-$300 annually for $1 million in coverage) and activates when your underlying policies are exhausted.
Common Insurance Mistakes in San Juan
- Underestimating rebuilding costs: Construction costs in Hidalgo County have increased significantly. Your dwelling coverage should reflect current local rebuilding costs, not what you paid for your home or its market value.
- Ignoring auto insurance gaps: Dropping comprehensive coverage on older vehicles seems logical until hail damages every panel. Valley weather makes comprehensive coverage valuable longer than in other regions.
- Assuming renters don’t need insurance: Your landlord’s policy covers the building, not your possessions. San Juan apartment and rental home residents need separate renters insurance for their belongings and liability.
- Not documenting possessions: After a loss, you’ll need to prove what you owned. Walk through your home with video, capture serial numbers, and store the documentation digitally.
- Letting policies auto-renew without review: Insurance needs change annually. New purchases, home improvements, or life events should trigger policy updates.
- Choosing the lowest deductible without math: A $500 deductible sounds better than $1,000, but the premium difference might make the higher deductible smarter if you have emergency savings.
Frequently Asked Questions About Insurance in San Juan TX
What’s the average cost of homeowners insurance in San Juan?
Homeowners insurance in San Juan TX typically runs $1,200 to $2,100 annually for a $200,000 home, but numerous factors affect your specific rate. Construction type matters—brick homes often cost less to insure than frame. Your roof’s age and material significantly impact premiums, as do security systems and proximity to fire hydrants. The biggest cost drivers are usually your chosen deductibles, coverage limits, and any added protections like flood or extended replacement cost. Rather than focusing solely on premium, consider the coverage-to-cost ratio and the insurer’s reputation for handling claims fairly.
How does living near the border affect my insurance options?
Proximity to the Mexico border creates unique insurance considerations that some national providers might not fully appreciate. Auto insurance needs to consider occasional cross-border travel (even if just to nearby Mexican border towns), though most US policies provide limited Mexico coverage at best—you’ll typically need separate Mexican auto insurance for trips beyond the border zone. Homeowners insurance should account for the Valley’s specific weather patterns that differ from other Texas regions. Some insurers offer bilingual policy documents and customer service, which can be valuable for multilingual San Juan households. Most importantly, work with providers who understand Hidalgo County’s specific risk profile rather than applying general Texas averages.
Can I get insurance discounts for home safety features?
Absolutely—most insurers offer discounts for home safety and security features that reduce risk. In San Juan, commonly recognized features include monitored alarm systems (especially those with fire detection), storm shutters or impact-resistant windows, updated electrical and plumbing systems, and reinforced roofing materials. Some providers offer additional discounts for newer homes (less than 10-15 years old) or homes that have undergone recent major renovations. Don’t assume your insurer knows about these features; provide documentation and ask specifically about available discounts. Combining home and auto policies with the same provider typically saves 15-25%, and paying annually rather than monthly can save installment fees.
What should I do immediately after an auto accident in the San Juan area?
After ensuring everyone’s safety and calling 911 if there are injuries, document everything systematically. Take photos of all vehicles involved from multiple angles, including license plates and visible damage. Capture the intersection or location signs to establish where the accident occurred. Exchange insurance information with other drivers, but avoid discussing fault at the scene—that’s for the insurers and possibly police to determine. Notify your insurance company within 24 hours, even if the accident seems minor. In Hidalgo County, it’s wise to file a police report for any significant accident as it creates an official record. If you need repairs, ask your insurer about preferred shops in the San Juan area that guarantee their work and use proper repair procedures.
How often should I review and update my insurance policies?
Mark your calendar for an annual insurance review—perhaps when you do your taxes or at the start of the year. Life changes that should trigger immediate reviews include marriage or divorce, having a child, significant home renovations, purchasing valuable items, changing jobs, or buying/selling vehicles. Even without major life events, annually check that your coverage limits still match your home’s rebuilding cost (construction inflation has been significant) and your possessions’ value. Review deductibles to ensure they still match your financial situation. Finally, shop comparisons every 2-3 years to ensure you’re getting competitive rates, but balance price against service quality—the cheapest policy isn’t valuable if the company fights every claim.
Does health insurance differ in San Juan compared to other Texas cities?
Health insurance in San Juan TX operates under the same Texas regulations as elsewhere, but network availability creates practical differences. The Rio Grande Valley has its own healthcare ecosystem with major providers like DHR Health, Doctors Hospital at Renaissance, and McAllen Medical Center. When choosing plans, verify that your preferred local doctors and specialists are in-network. Some national insurance plans have limited Valley networks, while others designed specifically for South Texas offer broader local access. Additionally, some plans might include cross-border coverage options or telemedicine services tailored to Valley residents. Prescription drug networks also vary—check that your regular medications are covered at local pharmacies.
Are there special considerations for insuring older homes in San Juan?
San Juan’s historic neighborhoods have charm but present unique insurance challenges. Older homes often have outdated electrical, plumbing, and roofing systems that insurers view as higher risk. You might need updated inspections to qualify for standard coverage, or you may need a specialized policy for older homes. Replacement cost coverage becomes complicated—insuring an older home for replacement cost might mean reconstructing with modern materials to current codes, which can exceed the home’s market value. Some insurers offer “actual cash value” coverage for older homes, which accounts for depreciation. Document any updates you’ve made (rewiring, roof replacement, plumbing upgrades) as these can significantly reduce premiums. Consider adding ordinance or law coverage to help pay for bringing the home up to code if damaged.
Conclusion
Navigating insurance in San Juan TX doesn’t have to be overwhelming when you approach it systematically. Start by understanding the specific risks our Valley location presents—from weather patterns to regional economic factors. Build your coverage around these realities rather than generic policies. Remember that the right insurance isn’t just about checking boxes; it’s about creating genuine security for your family, your home, and your financial future.
The most successful San Juan insurance strategies balance adequate protection with affordable premiums through smart bundling, regular reviews, and working with providers who understand our community. Whether you’re protecting a generations-old family home or just starting out in your first apartment, taking the time to get insurance right means you can focus on enjoying everything San Juan offers—the festivals, the food, the community connections—without underlying worry about what might go wrong. Your peace of mind is worth the investment.